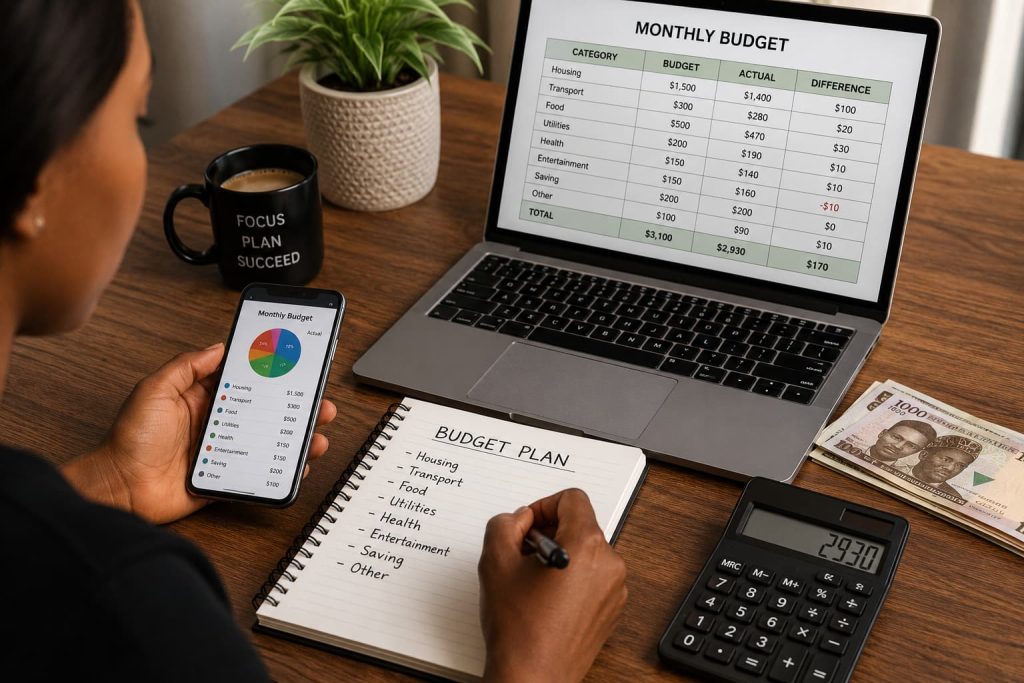
Many people do not have a money problem as much as they have a money-visibility problem. Learning how to budget money is an essential step toward taking control of your finances, reducing unnecessary spending, and achieving your financial goals. Whether you are a complete beginner or struggling to manage your income, this simple step-by-step guide will show you how to create, follow, and maintain a practical budget that works.
You receive your salary, business income, freelance payment, or other income. You pay rent, buy food, transport yourself, support family members, pay for airtime and data, handle unexpected expenses—and before you know it, the money is gone.
Then comes the familiar question:
“Where did all my money go?”
Learning how to budget money helps you answer that question before your money disappears.
A budget is not a punishment. It is simply a plan for deciding what your money should do before circumstances, pressure, impulse purchases, or unexpected expenses decide for you.
For people living in Nigeria, budgeting can be particularly important because everyday costs can change, incomes may be irregular, and many households have responsibilities that extend beyond their immediate personal expenses.
The goal is not to create a perfect spreadsheet or follow somebody else’s percentage formula. The goal is to create a realistic plan that helps you:
• Cover your essential expenses.
• Avoid unnecessary spending.
• Prepare for expected and unexpected costs.
• Save consistently.
• Reduce financial stress.
• Make better decisions with the income you already have.
• Work gradually toward larger financial goals.
This beginner-friendly guide explains how to budget your money step by step, including how to calculate your income, track your spending, create spending limits, save, handle irregular income, and adjust your budget when life changes.
What Does Budgeting Money Actually Mean?
A budget is a plan for how you intend to use your income over a specific period, usually a month.
At its simplest, personal budgeting answers four questions:
1. How much money is coming in?
2. Where is my money currently going?
3. What must I spend money on?
4. What do I want my money to accomplish?
A working monthly budget helps you compare your available income with your planned expenses.
The basic principle is simple:
Income − Expenses = Money Remaining
However, good budgeting goes beyond simply hoping that something remains at the end of the month.
A stronger approach is to give your income specific jobs. Some money may be allocated to food, housing, transportation, savings, debt repayment, family responsibilities, or personal spending.
Financial literacy involves developing the knowledge and skills needed to manage financial resources effectively. The Central Bank of Nigeria identifies financial literacy as an important part of helping consumers understand financial decisions, risks, and opportunities.
A budget is one practical tool for applying those skills.
Why Learning How to Budget Money Matters
Budgeting will not automatically increase your income.
However, it can help you make better decisions with the money you currently earn.
Without a budget, it is easy to spend based on:
• What feels urgent at the moment.
• Pressure from other people.
• Impulse purchases.
• Habits.
• Assumptions about how much money you have left.
With a budget, you can make decisions based on a clearer picture of your finances.
Budgeting helps you see financial problems earlier
Suppose you earn ₦250,000 per month.
Without tracking your spending, you may feel that you are managing reasonably well until you discover that your expenses regularly exceed your income.
A budget can reveal problems such as:
• Transportation costs that have increased.
• Frequent food deliveries or eating out.
• Multiple subscriptions.
• Unplanned cash withdrawals.
• High debt repayments.
• Repeated financial support that has not been planned for.
• Small daily expenses that become large monthly expenses.
The Consumer Financial Protection Bureau similarly recommends recording income, tracking actual spending, identifying bill due dates, and comparing spending with available income when building a realistic budget.
Budgeting gives savings a place in your financial life
Many people save using this approach:
“I will save whatever remains at the end of the month.”
The problem is that something else can always take the remaining money.
A budget allows you to intentionally allocate money toward goals such as:
• An emergency fund.
• Rent.
• School fees.
• A business goal.
• A major purchase.
• Investment, where appropriate.
• Debt reduction.
Budgeting helps you prepare for irregular expenses
Not every expense happens monthly.
Examples include:
• School fees.
• Annual rent.
• Vehicle repairs.
• Medical expenses.
• Family events.
• Religious or charitable commitments.
• Professional fees.
• Birthdays and celebrations.
• Travel.
A good budget does not ignore these expenses simply because they are not due this month.
How to Budget Money: A Simple Step-by-Step Process
The easiest way to create a budget is to work through your finances in stages.
Do not try to build a perfect budget on your first attempt.
Your first budget is a starting point. You will improve it as you learn more about your actual spending.
Step 1: Calculate Your Monthly Income
Start by determining how much money is realistically available to you.
Include income such as:
• Salary or wages.
• Business income.
• Freelance income.
• Professional fees.
• Commission.
• Rental income.
• Regular side-hustle income.
• Other reliable income.
If you earn a fixed salary
Use your actual take-home pay—the money available to you after deductions.
For example:
| Income Source | Monthly Amount |
| Salary | ₦300,000 |
| Side hustle | ₦50,000 |
| Total Income | ₦350,000 |
Your starting point for the monthly budget would be ₦350,000.
If your income changes every month
Do not automatically budget based on your best month.
Instead, look at several recent months and identify a conservative amount you can reasonably expect.
For example:
| Month | Income |
| 1st Month | ₦180,000 |
| 2nd Month | ₦250,000 |
| 3rd Month | ₦210,000 |
| 4th Month | ₦160,000 |
Rather than planning your lifestyle around the highest month, you might create a basic budget around a more conservative income level.
This reduces the risk of spending as though a high-income month will repeat automatically.
Important rule: Budget available income, not expected money
Avoid including money that has not yet arrived unless you have a clear reason to rely on it.
For example, do not build your monthly budget around:
• A client payment that is uncertain.
• A promised loan.
• An expected bonus that has not been confirmed.
• Money somebody says they will send.
• A business sale that has not yet happened.
Budgeting works best when based on money you can reasonably count on.
Step 2: Track Where Your Money Is Actually Going
This is one of the most important steps in budgeting for beginners.
Many people create budgets based on what they think they spend.
A more useful budget is based on what they actually spend.
Review your spending for the previous month or several weeks.
Check:
• Bank statements.
• Mobile banking transactions.
• Cash withdrawals.
• POS transactions.
• Transfer history.
• Mobile money transactions.
• Receipts.
• Bills.
Do not forget cash spending.
Small cash purchases can easily disappear from memory.
The CFPB recommends looking at actual spending rather than editing your history to reflect what you believe you “should” have spent.
Common categories to track
Your spending might include:
Housing
• Rent contribution.
• Service charges.
• Repairs.
Food
• Groceries.
• Market purchases.
• Restaurants.
• Takeaway food.
Transportation
• Fuel.
• Public transport.
• Ride-hailing.
• Vehicle maintenance.
Utilities
• Electricity.
• Water.
• Cooking gas.
• Internet.
Communication
• Airtime.
• Data subscriptions.
Financial obligations
• Loan repayments.
• Debt repayment.
• Insurance, where applicable.
Family responsibilities
• Support for parents.
• Children.
• School expenses.
• Other agreed responsibilities.
Personal spending
• Clothing.
• Entertainment.
• Hobbies.
Savings and financial goals
• Emergency savings.
• Short-term goals.
• Long-term goals.
You do not need twenty complicated categories.
Start with enough categories to understand your spending clearly.
Step 3: Separate Fixed Expenses From Variable Expenses
Once you know where your money goes, separate your expenses into two broad groups.
Fixed expenses
These are expenses that are usually predictable or relatively consistent.
Examples may include:
• Rent.
• Regular loan repayments.
• School fees when converted into a monthly savings amount.
• Insurance premiums.
• Regular subscriptions.
The amount may not always be identical, but the expense is generally expected.
Variable expenses
These change from month to month.
Examples include:
• Food.
• Transportation.
• Electricity.
• Data.
• Entertainment.
• Personal purchases.
• Household supplies.
Variable expenses are often where you have more flexibility.
However, flexibility does not mean these expenses are unimportant.
Food and transportation, for example, are variable but essential.
The goal is to identify which costs are:
1. Essential and difficult to reduce.
2. Essential but adjustable.
3. Optional or discretionary.
This distinction makes later decisions easier.
Step 4: List Your Financial Priorities
A budget should reflect reality.
Before allocating money to optional spending, identify the financial responsibilities that matter most.
A simple priority order may look like this:
Level 1: Essential living expenses
Examples:
• Housing.
• Food.
• Basic transportation.
• Utilities.
• Essential healthcare.
• Necessary communication.
Level 2: Required financial obligations
Examples:
• Minimum debt payments.
• Important family obligations you have committed to.
• Contractual financial responsibilities.
Level 3: Financial stability
Examples:
• Emergency savings.
• Necessary sinking funds for predictable future expenses.
Level 4: Financial goals
Examples:
• Additional debt repayment.
• Business capital.
• Long-term savings.
• Investing where appropriate for your circumstances and risk tolerance.
Level 5: Lifestyle and discretionary spending
Examples:
• Entertainment.
• Eating out.
• Non-essential shopping.
• Luxury purchases.
Your exact order may differ.
The important principle is this:
Do not allow low-priority spending to regularly consume money needed for high-priority responsibilities.
Step 5: Set Spending Limits for Each Category
Now you can create a simple budget plan.
Assume, for example, that a person has ₦350,000 available for the month.
A hypothetical budget could look like this:
| Category | Planned Amount |
| Housing | ₦70,000 |
| Food | ₦80,000 |
| Transportation | ₦35,000 |
| Utilities | ₦25,000 |
| Airtime and Data | ₦10,000 |
| Family Responsibilities | ₦30,000 |
| Debt Repayment | ₦25,000 |
| Emergency Saving | ₦30,000 |
| Personal/Discretionary Spending | ₦20,000 |
| Future Expense Fund | ₦25,000 |
| Total | ₦350,000 |
This is only a hypothetical example.
It is not a recommended formula for everyone.
Someone paying high rent may allocate more to housing. Someone with no debt may allocate more toward savings or another goal. Someone earning less may first need to focus primarily on essential expenses.
Your budget should reflect your actual circumstances.
Step 6: Give Every Naira a Job
One effective budgeting principle is to assign a purpose to the money you earn.
Instead of seeing ₦100,000 as one large amount of available money, you may divide it mentally or physically into planned purposes.
For example:
• ₦30,000 for food.
• ₦15,000 for transportation.
• ₦10,000 for utilities.
• ₦15,000 for savings.
• ₦10,000 for debt.
• ₦10,000 for family obligations.
• ₦10,000 for personal spending.
The goal is not to make your budget restrictive.
The goal is to avoid accidentally spending money that already has an important purpose.
This approach can be especially useful when several financial demands compete for the same income.
Step 7: Include Savings in Your Budget
Saving is easier to manage when it is part of your plan.
Even if you cannot save a large amount, consider starting with a realistic figure.
For example:
• ₦5,000.
• ₦10,000.
• ₦20,000.
The amount will depend on your income and essential expenses.
The important point is consistency and realism.
Do not create a savings target so aggressive that you repeatedly fail to meet your essential needs and then abandon the budget entirely.
A better approach is to start with an amount you can sustain and increase it as your income or financial position improves.
You can learn more about preparing for unexpected financial shocks in our guide on Why Every Nigerian Needs an Emergency Fund Strategy Before It’s Too Late.
Step 8: Plan for Expenses That Do Not Occur Every Month
One common budgeting mistake is forgetting future expenses.
Suppose you expect school fees of ₦240,000 in six months.
Instead of waiting until the deadline approaches, you could divide the expected cost over the available months:
₦240,000 ÷ 6 months = ₦40,000 per month
You could then include ₦40,000 in your monthly budget.
This is sometimes called a sinking fund—money set aside gradually for a known future expense.
The same approach can be used for:
• Rent.
• School fees.
• Vehicle maintenance.
• Travel.
• Annual subscriptions.
• Professional fees.
• Planned celebrations.
This can make large expenses less disruptive.
Step 9: Track Your Spending During the Month
Creating a budget is only the planning stage.
The next challenge is using it.
Choose a method you can realistically maintain.
You could use:
• A notebook.
• A spreadsheet.
• A budgeting app.
• Your banking app transaction history.
• A notes application on your phone.
The best budgeting tool is not necessarily the most sophisticated one.
It is the one you will consistently use.
A simple weekly review
Once each week, check:
1. How much did I plan to spend?
2. How much have I actually spent?
3. Which categories are close to their limits?
4. Have any unexpected expenses appeared?
5. Do I need to adjust the rest of the month’s spending?
Weekly reviews are often easier than waiting until the end of the month.
They give you an opportunity to correct problems before they become larger.
Step 10: Adjust Your Budget When Reality Changes
Your first budget will probably not be perfect.
That is normal.
Prices change. Transportation costs change. Family responsibilities change. Income can increase or fall.
A budget should be a living financial plan, not a document you are afraid to modify.
If food costs rise, for example, you may need to:
• Increase your food allocation.
• Reduce a less important category.
• Find ways to reduce food waste.
• Adjust shopping habits.
• Increase income where realistically possible.
If your income falls, you may need to:
• Protect essential expenses first.
• Reduce discretionary spending.
• Pause lower-priority goals temporarily.
• Review debt obligations carefully.
• Avoid automatically relying on expensive borrowing to maintain an unsustainable lifestyle.
A budget that changes with reality is usually more useful than a rigid budget that no longer matches your life.
How to Budget Money When Your Income Is Low
Budgeting cannot solve every financial problem.
If your income is genuinely insufficient to cover essential living costs, the solution cannot simply be to “budget harder.”
This is an important distinction.
A person may already be financially disciplined and still struggle because:
• Their income is too low.
• Essential costs have increased.
• They support several dependants.
• They have unavoidable debt.
• Their employment or business income is unstable.
However, budgeting can still help you understand the gap.
Start with financial survival priorities
List:
1. Food.
2. Housing.
3. Essential transportation.
4. Basic utilities.
5. Essential healthcare.
6. Required debt obligations.
Then identify what can realistically be reduced or delayed.
Avoid pretending that the numbers balance
If your monthly income is ₦100,000 but your essential expenses are ₦140,000, your budget has revealed a ₦40,000 gap.
Do not hide that gap by simply creating unrealistic spending limits.
Instead, consider practical responses such as:
• Reducing a cost.
• Renegotiating an obligation where possible.
• Increasing income.
• Selling an unnecessary asset where appropriate.
• Seeking lower-cost alternatives.
• Reviewing expensive debt.
A budget is valuable partly because it exposes financial problems clearly.
How to Budget Money With Irregular Income
Irregular income requires a slightly different approach.
This may apply to:
• Business owners.
• Freelancers.
• Commission earners.
• Seasonal workers.
• Traders.
• People with multiple income streams.
Build your lifestyle around a conservative income level
Do not treat a good month as your permanent income.
Identify a baseline amount that you can reasonably use for essential planning.
Separate essential spending from flexible spending
For example:
Essential
• Food.
• Housing.
• Transportation.
• Utilities.
Flexible
• Entertainment.
• Optional shopping.
• Non-essential upgrades.
When income is higher, you can allocate additional money deliberately rather than immediately increasing lifestyle spending.
Create a buffer
When possible, use stronger months to prepare for weaker months.
This can involve building:
• Emergency savings.
• A business reserve.
• A household buffer.
The exact strategy depends on your income pattern and financial obligations.
Should You Use the 50/30/20 Budget Rule?
The 50/30/20 rule is a popular budgeting framework.
It generally divides income into broad categories for:
• Needs.
• Wants.
• Savings and financial goals.
It can be useful as a starting point, but it should not be treated as a universal rule.
For many people, particularly those facing high housing, food, transportation, or family costs, a fixed percentage formula may not reflect reality.
For example, someone with very high essential expenses may need substantially more than half of their income for necessities.
Another person living with fewer financial obligations may have more flexibility.
The lesson is:
Use budgeting frameworks as guides, not laws.
Your budget should be based on your actual income, responsibilities, costs, and goals.
A Simple Monthly Budget Example for a Nigerian Salary Earner
Assume a hypothetical employee has a monthly take-home income of ₦400,000.
A possible budget might look like this:
| Category | Amount |
| Housing/Rent Fund | ₦70,000 |
| Food | ₦90,000 |
| Transportation | ₦40,000 |
| Utilities | ₦25,000 |
| Airtime/Data | ₦10,000 |
| Family Responsibilities | ₦35,000 |
| Debt Repayment | ₦30,000 |
| Emergency Fund | ₦40,000 |
| Future Expenses Fund | ₦30,000 |
| Personal Spending | ₦20,000 |
| Entertainment/Others | ₦0,000 |
| Total | ₦400,000 |
Again, this is a hypothetical example—not a prescription.
The purpose is to show how a monthly budget can allocate income across different responsibilities.
Common Budgeting Mistakes Beginners Make
Learning how to budget money can help you control spending, save consistently, and make meaningful progress toward your financial goals. However, creating a budget is only the beginning. Many beginners make simple mistakes that can cause their budget to fail. Here are 10 common budgeting mistakes to avoid.
1. Creating an Unrealistic Budget
One of the most common budgeting mistakes is creating a budget that is too strict to maintain. Cutting out every enjoyable expense may look good on paper but can be difficult to sustain.
Instead, create a realistic budget that allows room for essential expenses, savings, and some reasonable personal spending.
2. Forgetting Irregular Expenses
Some expenses do not occur every month, but they still need to be included in your financial plan.
Expenses such as school fees, annual bills, repairs, medical costs, birthdays, and family events can put pressure on your finances when you fail to plan for them.
Set aside a small amount regularly for predictable irregular expenses.
3. Tracking Only Large Expenses
Focusing only on major expenses such as rent, food, or transportation can cause you to overlook small purchases.
Daily spending on snacks, drinks, subscriptions, airtime, data, and impulse purchases can add up significantly over time.
Track your spending for at least one month to identify where your money is actually going.
4. Spending Expected Income Before Receiving It
Another common mistake is spending money based on income you expect to receive rather than money you already have.
A promised payment, bonus, business income, or financial support may be delayed or may not arrive as expected.
Build your budget around money you have actually received whenever possible.
5. Saving Without an Emergency Fund
Saving for a specific goal is important, but unexpected expenses can quickly consume those savings if you do not have a separate emergency fund.
An emergency fund can help you handle unexpected costs without relying heavily on loans or credit.
Start small and gradually build an emergency reserve that fits your circumstances.
6. Ignoring Family Responsibilities
For many people, family support is a genuine part of their financial responsibilities. Ignoring predictable obligations can make your budget unrealistic.
If you regularly support relatives, contribute to household expenses, or help with family needs, account for these commitments when planning your spending.
Budget for predictable family responsibilities while maintaining reasonable limits.
7. Failing to Review Your Budget
Your income, expenses, priorities, and financial goals can change over time. A budget that worked six months ago may no longer reflect your current situation.
Review your budget regularly and adjust categories when your circumstances change.
8. Relying on Memory Instead of Tracking Expenses
Trying to remember where every naira went is unreliable. Small purchases are particularly easy to forget.
Without accurate tracking, you may underestimate your spending and overestimate how much money you have available.
Record your expenses using a notebook, spreadsheet, budgeting app, or another method you can consistently maintain.
9. Treating the Budget as a Punishment
A budget should help you make better decisions with your money—not make you feel guilty about every purchase.
If your budget is so restrictive that you cannot enjoy any reasonable spending, you may eventually abandon it altogether.
Give every category a realistic limit and include some room for personal or discretionary spending.
10. Giving Up After One Bad Month
Overspending in one category does not mean your entire budgeting plan has failed.
Instead of abandoning your budget, review what happened and identify what needs to change.
Ask yourself:
• Was the expense unavoidable?
• Was my original estimate unrealistic?
• Did I forget an important expense?
• Was the purchase unnecessary or impulsive?
• What can I adjust next month?
The goal of budgeting is progress, not perfection. Learning from mistakes and making better financial decisions consistently is what makes a budget effective over time.
How to Make Your Budget Easier to Follow
A good budget should be practical enough to survive ordinary life.
Automate what you can
Where appropriate, you may arrange automatic transfers for savings or important financial goals.
However, always ensure that automatic commitments do not create unnecessary pressure on essential expenses.
Use separate accounts carefully
Some people find it helpful to separate:
• Spending money.
• Savings.
• Emergency funds.
• Business funds.
The exact arrangement depends on the financial products available to you and the fees and conditions attached to them.
Always understand the terms of any financial account or product you use.
Set a realistic personal spending amount
Completely ignoring personal enjoyment can cause some budgets to become difficult to maintain.
A realistic budget can include controlled discretionary spending if your finances allow.
Review your progress regularly
A monthly review is a useful minimum.
Ask:
• Did I spend more or less than planned?
• Which category was most difficult?
• Did I save anything?
• Did unexpected expenses occur?
• What should change next month?
Budgeting Tips That Can Help You Manage Money Better
Learning how to budget money is easier when you have a practical system you can follow consistently. A good budget helps you understand where your money goes, prioritize important expenses, control unnecessary spending, and work toward your financial goals. Here are 10 budgeting tips that can help you manage your money better.
1. Start With What You Earn Now
Build your budget around your actual income rather than money you expect to receive in the future.
Do not rely on a hoped-for salary increase, bonus, business profit, or payment that has not yet arrived.
Base your spending plan on reliable income and treat unexpected income as extra until it is received.
2. Track Your Spending Before Making Major Cuts
Before deciding what to eliminate, spend some time tracking where your money actually goes.
You may discover that your biggest spending problem is different from what you expected.
Record your expenses for at least one month and use the information to make informed adjustments.
3. Focus on Your Biggest Spending Leaks
Not every expense deserves the same attention. Cutting a large recurring expense can sometimes make a bigger difference than worrying about every small purchase.
Look for areas such as excessive subscriptions, expensive debt payments, frequent takeout, unnecessary transportation costs, or lifestyle expenses.
Identify your three biggest spending leaks and address them first.
4. Make Savings Part of Your Budget
Do not treat saving money as something you will do only if you have cash left at the end of the month.
Instead, make savings a planned part of your budget alongside your essential expenses.
Set a realistic savings target and automate or separate the money when possible.
5. Review Your Recurring Expenses
Small recurring payments can quietly consume a significant portion of your income.
Review subscriptions, memberships, service charges, and other automatic payments regularly.
Cancel services you rarely use and look for cheaper alternatives where practical.
6. Plan for Predictable Family Commitments
Family responsibilities can be an important part of your financial plan. Ignoring predictable obligations can make your budget unrealistic.
If you regularly contribute to household expenses, support relatives, or prepare for family events, include these commitments in your budget.
Set reasonable limits for family-related spending while protecting your essential financial priorities.
7. Separate Needs From Wants
One of the most useful budgeting skills is learning to distinguish between expenses you need and expenses you simply want.
Housing, food, transportation, utilities, and essential healthcare generally deserve priority over non-essential purchases.
Before making a purchase, ask yourself whether it is a need, a planned want, or an impulse purchase.
8. Avoid Comparing Your Budget With Someone Else’s Lifestyle
Your financial situation is unique. Different people have different incomes, responsibilities, debts, goals, and priorities.
Trying to copy someone else’s lifestyle can encourage unnecessary spending and financial pressure.
Build your budget around your own income, responsibilities, and financial goals.
9. Give Every Naira a Purpose
A budget becomes more effective when you know what you want your money to accomplish.
Assign your income to important categories such as housing, food, transportation, savings, debt repayment, investments, and personal spending.
Before spending, decide where your money should go instead of wondering where it went afterward.
10. Improve Your Budget Gradually
You do not need to completely transform your finances overnight.
An extreme budget may work for a few days but become difficult to maintain. Sustainable changes are more likely to become lasting financial habits.
Make one or two realistic improvements at a time, review your progress, and adjust as your circumstances change.
Budgeting and Financial Discipline
A budget gives you a plan.
Financial discipline helps you follow it.
This is where many people struggle.
You may know exactly what you should do with your money and still make decisions that conflict with your financial goals.
That does not necessarily mean you need another budgeting formula.
Sometimes the deeper issue is behavior.
For practical strategies on developing stronger money habits, read Financial Discipline Tips: 15 Habits to Take Control of Your Money.
Over time, budgeting and financial discipline can work together:
• Your budget provides direction.
• Your habits support consistency.
• Your financial goals provide motivation.
How Budgeting Supports Long-Term Wealth Building
Budgeting alone does not create wealth.
However, it can create the financial awareness and consistency needed for broader wealth-building activities.
When you understand your cash flow, you are better positioned to identify:
• How much you can realistically save.
• Whether debt is consuming too much income.
• Where unnecessary spending can be reduced.
• Whether you have capacity to pursue additional income.
• How much can potentially be allocated toward long-term financial goals.
Wealth building generally requires more than one action. It can involve earning, saving, managing risk, investing appropriately, and maintaining disciplined financial habits over time.
For more practical ideas, see 15 Wealth-Building Habits to Build Wealth in Nigeria and 10 Powerful Wealth Mindset Shifts That Transform Everything About Your Finances.
A Simple Budgeting Checklist for Beginners
Before the month begins, use this checklist.
Income
• I know my expected available income.
• I have not included uncertain money as guaranteed income.
Essential expenses
• I have listed my major living costs.
• I have included transportation.
• I have included food.
• I have included utilities.
• I have considered family responsibilities.
Financial obligations
• I have listed debt repayments.
• I know when important bills are due.
Savings and future planning
• I have allocated something toward savings if my circumstances allow.
• I am preparing gradually for predictable future expenses.
• I have considered emergency expenses.
Spending control
• I have set realistic limits.
• I have a way to track spending.
• I will review the budget during the month.
Frequently Asked Questions About How to Budget Money
1. How do I start budgeting for the first time?
To learn how to budget money, start by calculating your reliable income and reviewing your recent spending. Categorize your expenses, identify your priorities, set realistic spending limits, and track your spending throughout the month.
2. How much money should I save from my income?
There is no single savings amount that works for everyone. Your ideal amount depends on your income, essential expenses, debt, family responsibilities, and financial goals. Start with an amount you can maintain consistently and increase it as your finances improve.
3. What if my expenses are higher than my income?
Your budget has identified a financial gap. Review your expenses to determine what can realistically be reduced, eliminated, or renegotiated. You may also need to explore practical ways to increase your income. Avoid creating unrealistic spending limits that you cannot maintain.
4. Is the 50/30/20 budget rule good for everyone?
No. The 50/30/20 rule can provide a useful starting framework, but it does not work equally well for every financial situation. High housing costs, debt, family responsibilities, and irregular income may require a different approach.
5. How often should I review my budget?
Track your spending regularly, ideally throughout the week, and review your overall budget at least once a month. Regular reviews help you identify overspending early and make adjustments before small problems become larger financial challenges.
6. Should I budget based on my gross income or take-home pay?
For everyday budgeting, it is generally more practical to use the income you actually have available after taxes, pension contributions, and other automatic deductions. This gives you a clearer picture of the money available for spending, saving, and investing.
7. What should I include in a monthly budget?
A monthly budget should include essential expenses, debt payments, savings, investments, discretionary spending, and predictable irregular expenses. Depending on your circumstances, categories may include housing, food, transportation, utilities, healthcare, education, family support, and personal expenses.
8. How can I budget when my income is irregular?
If your income changes from month to month, base your essential spending on a conservative estimate rather than your highest-earning month. Prioritize necessities, build an emergency fund during stronger months, and adjust your discretionary spending according to your actual income.
9. How do I stop overspending when I have a budget?
Track your expenses as you spend rather than waiting until the end of the month. Set spending limits for problem categories, reduce impulse purchases, and review your progress regularly. A realistic budget is easier to follow than one with excessively strict limits.
10. Should I use a budgeting app or a spreadsheet?
Either can work. The best budgeting method is the one you can use consistently. A spreadsheet provides flexibility and control, while a budgeting app may make expense tracking more convenient. You can also start with a simple notebook if that is easier for you.
11. Can budgeting really help me build wealth?
Yes. A well-managed budget can help you control unnecessary spending, create room for savings and investing, reduce debt, and direct more of your income toward long-term financial goals. Budgeting itself does not create wealth, but it can provide the financial structure needed to build it consistently.
Conclusion
Learning how to budget money does not require complicated financial software, advanced mathematics, or financial expertise. What matters most is knowing how much you earn, understanding where your money goes, and deciding how you want to use it.
Start with these simple steps:
1. Calculate your income — Know how much money you reliably have available.
2. Track your spending — Record where your money actually goes instead of relying on memory.
3. Separate needs from wants — Prioritize essential expenses before discretionary spending.
4. Set realistic spending limits — Create limits you can realistically maintain.
5. Budget for savings and future expenses — Give your financial goals a specific place in your budget.
6. Monitor your progress — Review your spending regularly and identify areas that need improvement.
7. Adjust when circumstances change — Update your budget when your income, expenses, or financial priorities change.
Your first budget may not be perfect—and that is okay.
The goal of budgeting is not to predict every expense or eliminate every enjoyable purchase. It is to give you greater control over your money and make your financial decisions more intentional.
With consistent practice, budgeting can help you develop better spending habits, save more consistently, prepare for unexpected expenses, reduce financial stress, and create room for important financial goals.
You do not need to wait for a higher income to start. Start with the money you have today.
Write down your income. Track where your money currently goes. Identify what needs to change. Then create a realistic plan for where you want your money to go next month.
That simple process is the foundation of effective personal budgeting—and an important first step toward building a more secure financial future.
Start small. Stay consistent. Review your progress. Adjust when necessary. Your financial future is shaped by the decisions you make with your money today.
Financial Education Disclaimer
This article is provided for general financial education and informational purposes only. It does not constitute personalized financial, investment, legal, accounting, or tax advice. Your income, expenses, financial obligations, risk tolerance, goals, and circumstances may differ from those discussed in this article.
Financial information, regulations, economic conditions, interest rates, and financial products can change over time. Before making significant financial decisions, verify current information, terms, regulations, and requirements with relevant official institutions and appropriately qualified professionals.
For additional financial and economic information, readers may consult reputable international institutions such as the World Bank, International Monetary Fund (IMF), and International Finance Corporation (IFC).
Wealth Mindset does not guarantee the accuracy, completeness, or suitability of information for any individual’s financial situation. Readers are responsible for evaluating their circumstances and seeking professional advice where appropriate.
Joy, also known as MindsetCoach, is the publisher and personal finance educator behind WealthMindset.com.ng, a Nigerian platform dedicated to practical money management and wealth-building education. She writes about budgeting, saving, financial literacy, debt management, investing, income growth, and building healthier financial habits. Through clear, practical, and evidence-informed content, Joy helps readers understand their money, make smarter financial decisions, and develop a wealth-building mindset suited to real-life financial challenges in Nigeria.