Saving money is not simply about spending less. These personal finance tips to save money are about making deliberate decisions with the money you earn, reducing unnecessary expenses, and developing better financial habits. When you manage your income wisely, you can keep more of your money, prepare for unexpected expenses, avoid financial stress, and steadily work toward important goals such as building savings, investing, and achieving long-term financial security.
For many Nigerians, this is easier said than done. Food, transportation, rent, school fees, healthcare, electricity, airtime and data, family responsibilities, debt repayments, and unexpected expenses can quickly consume an income before there is anything left to save.
That is why effective money management requires more than telling yourself to “save more.”
You need a system.
These personal finance tips to save money are designed to help you build that system. They focus on practical habits you can apply whether you earn a salary, run a small business, freelance, work multiple jobs, or receive irregular income.
The goal is not to follow an unrealistic formula. It is to understand where your money is going, make better decisions with it, create financial breathing room, and gradually direct more money toward savings and long-term wealth building.
Central Bank of Nigeria financial-literacy framework similarly emphasizes having a personal financial plan or budget, prioritizing spending according to needs, increasing the ability to save, and learning to manage irregular income.
What Does It Mean to Save Money?
Saving money means deliberately setting aside part of your income instead of spending all of it immediately.
Savings can serve different purposes. You might save for:
• An emergency fund
• Rent
• School fees
• Healthcare
• A planned purchase
• A business opportunity
• A future investment
• Retirement
• A major personal goal
The important distinction is between saving and investing.
Savings are generally intended for money you may need relatively soon or for financial security. Investments are designed to potentially grow your money over a longer period but involve risk.
That distinction matters because money needed for an emergency should not necessarily be placed into an investment whose value can fall when you need it.
Once your basic financial foundation is stronger, investing can become part of your broader wealth-building strategy. The Securities and Exchange Commission Nigeria (SEC) advises investors to establish clear goals, understand their risk tolerance, research investments carefully, diversify appropriately, and consider professional guidance where necessary.
15 Personal Finance Tips to Save Money
Let’s explore 15 personal finance tips to save money, cut unnecessary spending, build better habits, and boost financial security.
1. Know Exactly How Much Money You Receive
One of the simplest money management tips is to begin with a realistic picture of your income.
If you do not know how much money is available to you, it becomes difficult to create a workable spending plan.
For someone earning a fixed salary, this may be relatively straightforward. But income can be more complicated if you:
• Run a small business
• Freelance
• Work on commission
• Have multiple jobs
• Receive seasonal income
• Earn from online work
• Depend partly on family or business income
Do not automatically treat every inflow as disposable income.
For example, a small-business owner may receive ₦500,000 during a month but still have business expenses, supplier payments, transportation costs, taxes or other obligations.
The amount entering your account is not necessarily the amount available for personal spending.
A simple approach
At the beginning of each month, calculate:
Total personal income − unavoidable deductions/obligations = money available for your financial plan
If your income changes significantly from month to month, use a conservative estimate rather than budgeting around your best month.
This reduces the risk of spending as though unusually high income will continue indefinitely.
2. Track Where Your Money Goes
You cannot improve what you do not measure.
For at least 30 days, record your spending. You can use a notebook, spreadsheet, banking records or a budgeting application.
Divide expenses into broad categories such as:
| Category | Examples |
| Housing | Rent, service charges |
| Food | Groceries, meals, snacks |
| Transportation | Fuel, public transport, ride-hailing |
| Utilities | Electricity, water |
| Communication | Airtime, data |
| Family | Support and household obligations |
| Debt | Loan repayments |
| Health | Medication, consultations |
| Personal | Clothing, entertainment |
| Savings | Emergency fund and goals |
| Investing | Long-term investments |
Do not judge yourself while tracking.
The purpose is to discover the truth.
You may discover that one large expense is responsible for most of your financial pressure. Alternatively, you may discover that numerous small purchases are gradually consuming a significant amount.
Both findings are useful.
3. Create a Budget Before You Spend
A budget is simply a plan for how you intend to use your income.
It is not a punishment.
A good budget gives every naira a purpose before the money disappears.
The CBN’s financial-literacy framework specifically highlights the importance of having a budget, adhering to it and prioritizing spending according to pressing needs rather than wants.
Your budget should account for:
1. Essential expenses
2. Financial obligations
3. Savings
4. Debt repayment
5. Personal spending
6. Long-term financial goals
The key principle
Do not copy somebody else’s budget percentages blindly.
A person earning ₦200,000 with low housing costs and no dependants may have a completely different financial situation from someone earning ₦700,000 while supporting parents, children and paying high rent.
Your budget should reflect your actual circumstances.
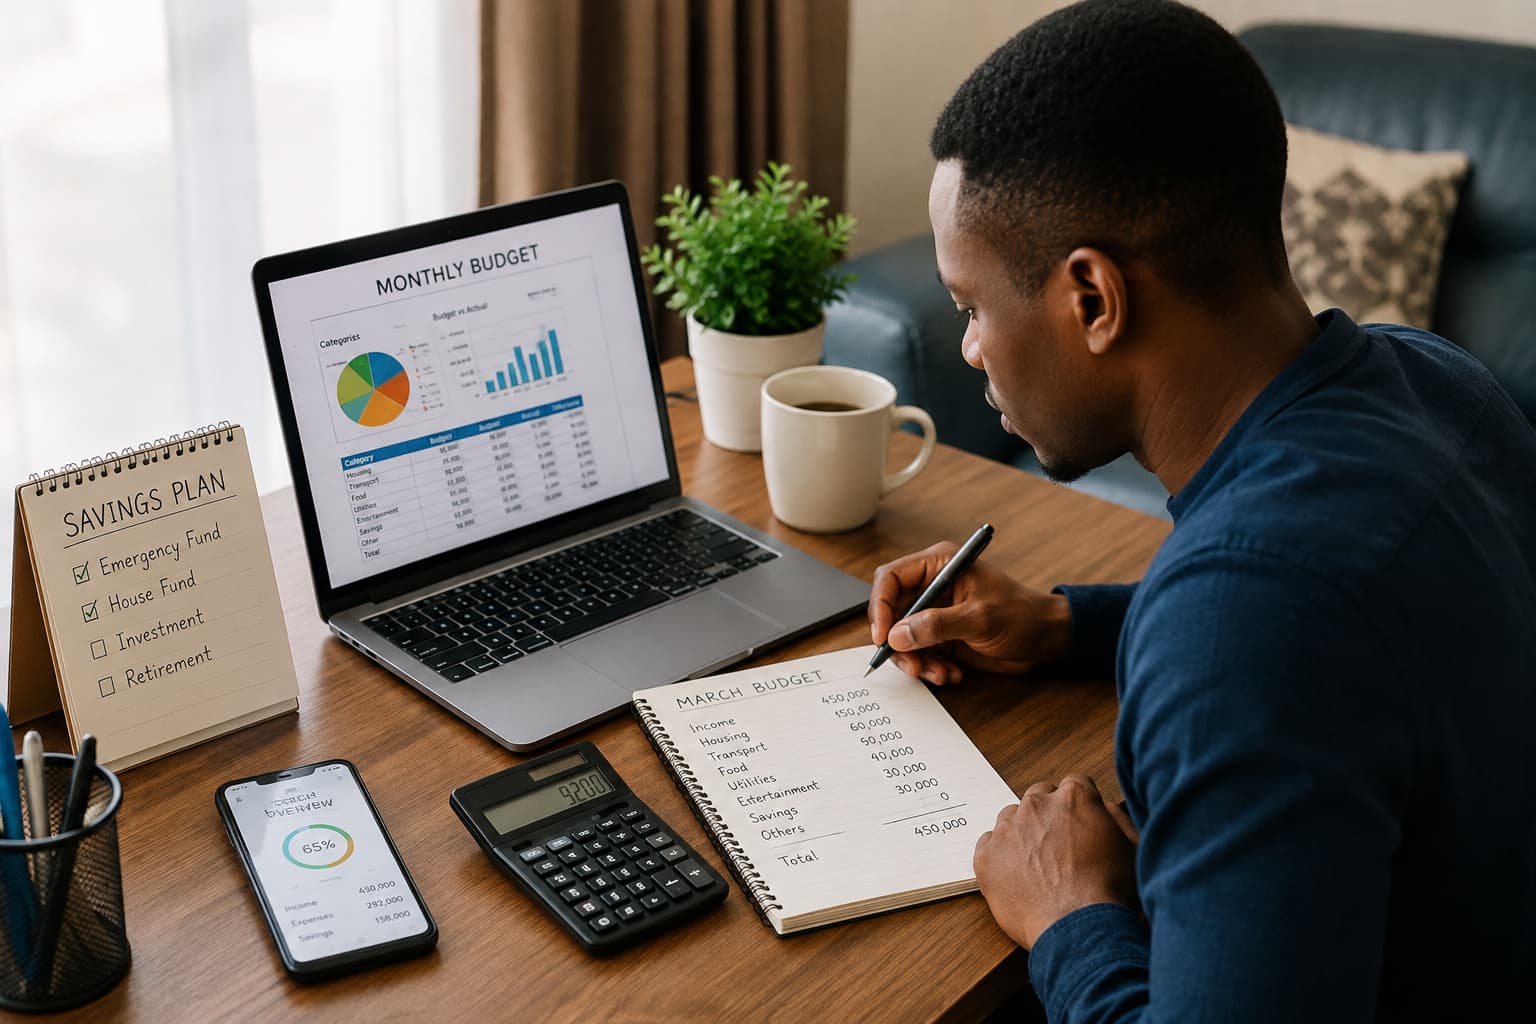
Before your income disappears into monthly expenses, learn budgeting in Nigeria strategies to plan spending, prioritize needs, save consistently, and make every naira count toward your goals.
4. Pay Yourself First
One of the most effective simple personal finance tips is to save before discretionary spending begins.
If you wait until the end of the month to save whatever remains, you may discover that nothing remains.
Instead, treat savings as one of your planned financial obligations.
For example, suppose your hypothetical monthly income is ₦300,000.
You could decide that immediately after receiving your income, you will move ₦30,000 into a dedicated savings account.
That does not mean ₦30,000 is the correct amount for everyone. It is simply an example of making saving intentional.
The principle is:
Income → planned savings → essential spending → discretionary spending
rather than:
Income → spending → whatever remains becomes savings
Automating transfers where your bank or financial service provides that feature can make the habit easier to maintain.
5. Build an Emergency Fund
An emergency fund protects your savings plan from unexpected events.
Imagine saving for a long-term goal and then suddenly facing:
• A medical bill
• Emergency transportation costs
• A major household repair
• Temporary loss of income
• An urgent family responsibility
Without an emergency reserve, you may have to borrow money or abandon another financial goal.
Your emergency fund should therefore be treated differently from money intended for holidays, gadgets or investments.
Start with an achievable target.
If you cannot immediately build several months of expenses, do not use that as an excuse to save nothing. Begin with a smaller emergency reserve and increase it gradually.
Important distinction
An emergency fund is not meant to generate maximum investment returns.
Its primary purpose is accessibility and financial resilience.
Unexpected expenses can derail your finances. Learn how an emergency fund strategy can help you prepare for urgent costs, reduce financial stress, and avoid relying on debt when surprises happen.
6. Separate Needs From Wants
This is one of the most powerful tips for managing money.
Before spending, ask:
“Do I need this now, or do I simply want it?”
Needs generally include things required for basic living and important responsibilities.
Wants may include:
• Upgrading a functioning phone
• Frequent restaurant meals
• Unplanned shopping
• Entertainment subscriptions
• Impulse purchases
• Buying things because they are discounted
A want is not automatically bad.
The problem occurs when wants consistently compete with essential expenses, savings and financial goals.
A useful rule is to create room for enjoyment without allowing lifestyle spending to consume money meant for your future.
7. Reduce Recurring Expenses
One of the easiest places to find savings is in expenses that repeat every month.
Review:
• Streaming subscriptions
• Data plans
• Unused memberships
• Banking charges
• Delivery expenses
• Frequent ride-hailing
• Eating out
• Digital subscriptions
• Unnecessary service upgrades
Suppose you discover that several small subscriptions collectively cost ₦15,000 every month.
Cancelling services you rarely use could potentially free up ₦180,000 over a year.
The calculation is straightforward:
₦15,000 × 12 months = ₦180,000
That is a hypothetical example, not a promise of what any particular reader will save.
The bigger lesson is that recurring expenses deserve attention because a small monthly amount can become significant over time.
8. Control Impulse Spending
Impulse spending happens when you make a purchase without adequately considering whether it fits your priorities.
Digital payments can make this particularly easy because spending may feel less tangible than handing over physical cash.
Before making a non-essential purchase, introduce a waiting period.
For example:
• Small discretionary purchase: wait a few hours.
• More expensive purchase: wait 24–72 hours.
• Major purchase: compare alternatives and review your budget first.
Ask yourself:
1. Did I plan for this?
2. Can I afford it without borrowing?
3. Do I actually need it?
4. Will buying it interfere with an important financial goal?
5. Is there a cheaper alternative?
You may still decide to buy it.
The purpose is not to eliminate enjoyment. It is to replace automatic spending with deliberate spending.
9. Shop With a Plan
Food and household purchases can become significant expenses when shopping is unplanned.
Before going shopping:
• Make a list.
• Check what you already have.
• Set a spending limit.
• Compare prices where practical.
• Avoid buying unnecessary items simply because they are on promotion.
• Consider buying frequently used essentials in economical quantities when doing so genuinely reduces cost.
However, do not assume that buying in bulk is always cheaper.
A discounted product that you rarely use is not necessarily a saving.
Likewise, buying a larger quantity may create waste if the item expires before you can use it.
The objective is lower total cost, not simply a lower price on one purchase.
10. Give Every Financial Goal a Separate Purpose
Saving becomes easier when you know what you are saving for.
Instead of putting all your savings into one undifferentiated pool, consider creating separate goals such as:
• Emergency fund
• Rent
• School fees
• Business capital
• Investment
• Vacation
• Major purchase
This can help you avoid using money intended for one goal to finance another.
For example, money saved for annual rent should not be treated as spare cash simply because your rent payment is several months away.
A goal-based approach also makes progress easier to measure.
11. Learn to Manage Irregular Income
Not everyone receives the same amount every month.
Freelancers, traders, business owners, commission-based workers and many side-hustle earners may experience significant income fluctuations.
The solution is not to pretend that income is fixed.
Instead, build your financial system around variability.
A practical method
When income is high:
1. Cover essential obligations.
2. Set aside money for upcoming expenses.
3. Strengthen your emergency fund.
4. Save toward longer-term goals.
5. Avoid immediately increasing your lifestyle.
When income is lower:
1. Prioritize essentials.
2. Reduce discretionary spending.
3. Avoid unnecessary debt.
4. Use your financial reserves appropriately.
5. Review upcoming obligations early.
If your income varies substantially, consider creating a personal monthly salary.
For example, if your business produces ₦900,000 in one month and ₦400,000 in another, you could avoid treating the ₦900,000 month as permission to dramatically increase spending.
Instead, establish a sustainable amount for personal living expenses while keeping adequate business and personal reserves.
12. Increase Your Savings When Your Income Increases
A salary increase, bonus, successful side hustle or profitable business month can create an opportunity to improve your financial position.
But there is a common trap: lifestyle inflation.
Lifestyle inflation occurs when spending rises whenever income rises.
For example, someone who moves from earning ₦250,000 to ₦350,000 may immediately increase rent, entertainment, clothing, transportation and other spending until the additional ₦100,000 disappears.
Instead, consider directing part of every income increase toward:
• Emergency savings
• Debt reduction
• Investments
• Business development
• Education
• Long-term financial goals
You can still improve your lifestyle.
The key is to ensure that your financial progress grows alongside your lifestyle.
13. Reduce Expensive Debt
Debt can make saving considerably harder because part of your future income is already committed to past spending.
Start by listing your debts:
| Debt | Balance | Interest/Cost | Monthly Payment | Priority |
| Debt A | ₦___ | ___ | ₦___ | High |
| Debt B | ₦___ | ___ | ₦___ | Medium |
| Debt C | ₦___ | ___ | ₦___ | Low |
Pay particular attention to expensive debt and loans whose costs can significantly affect your cash flow.
Do not take a new loan simply to make your budget appear balanced.
Before borrowing, understand:
• Total amount repayable
• Interest and other charges
• Repayment frequency
• Penalties
• What happens if you miss payments
• Whether the loan is genuinely necessary
Taking control of your money requires more than earning more. Discover practical financial discipline tips to control spending, improve saving, manage income, and make better financial decisions.
14. Increase Income Instead of Cutting Everything
Saving money has a limit.
There is only so much you can reduce from essential expenses.
If your income is consistently insufficient to cover basic needs, the answer may not be another round of aggressive cost-cutting.
You may also need to increase income.
Depending on your circumstances, possibilities could include:
• Freelancing
• Consulting
• Selling products
• Tutoring
• Digital services
• Skilled trades
• Small-scale agriculture
• Online services
• Part-time work
• Expanding an existing business
The objective is not to chase every side hustle.
Choose an income opportunity that fits your skills, available time, capital and risk tolerance.
And remember that additional income is only useful for wealth building if you manage it well.
If every additional Naira earned is immediately consumed by additional spending, your financial position may not improve significantly.
15. Put Long-Term Savings to Work Carefully
Saving creates financial stability. But over the long term, many people also need to consider investing to pursue growth.
This is where financial education becomes important.
Do not invest simply because someone on social media claims that an opportunity is “guaranteed.”
The SEC Nigeria specifically warns Nigerians about unregistered online investment schemes and unrealistic or guaranteed-return promises. It advises the public to verify the registration status of investment platforms and operators before committing money.
The SEC also emphasizes understanding investment risk, researching opportunities, diversifying appropriately and aligning investments with financial goals and risk tolerance.
Before investing, ask:
• What exactly am I buying?
• How does it generate returns?
• What could cause me to lose money?
• How quickly can I access the money?
• Who regulates the product or operator?
• What fees apply?
• Does the investment match my goal and time horizon?
• Can I afford to lose some or all of the invested money?
Never confuse a high promised return with a safe investment.
Building financial security starts with consistent habits. Learn practical wealth building habits to manage money wisely, grow assets, and work toward long-term financial freedom in Nigeria.
A Simple Nigerian Example: Putting the Tips Together
Consider a hypothetical worker earning ₦400,000 per month.
This is not a recommended universal budget. It is simply an illustration of how financial priorities can be organized.
Suppose the person’s monthly plan looks like this:
| Purpose | Hypothetical Amount |
| Housing contribution/rent allocation | ₦100,000 |
| Food | ₦70,000 |
| Transportation | ₦40,000 |
| Utilities & communication | ₦30,000 |
| Family obligations | ₦35,000 |
| Debt repayment | ₦30,000 |
| Emergency savings | ₦25,000 |
| Long-term savings/investing | ₦30,000 |
| Personal/discretionary spending | ₦25,000 |
| Total | ₦385,000 |
That leaves ₦15,000 un-allocated.
Rather than automatically spending it, the person could assign it to a specific upcoming expense, additional savings, debt repayment or another legitimate priority.
The important lesson is not the exact percentages.
The lesson is that a financial plan should account for both today’s obligations and tomorrow’s needs.
If housing costs are much higher, the allocation may need to change. If there are children or significant medical expenses, priorities may look different. If there is no debt, more money could potentially go toward savings or investing.
A useful budget is flexible enough to reflect real life.
What If You Have a Low Income?
Saving can feel impossible when income is barely enough for necessities.
In that situation, avoid advice that implies you simply need more discipline.
If your essential expenses consume almost all your income, the problem may be a cash-flow problem, not a character problem.
Start with small improvements.
Focus on four areas:
1. Protect essentials
Prioritize food, housing, transportation, healthcare, utilities and other necessary obligations.
2. Eliminate avoidable leakage
Look for spending that does not provide enough value relative to its cost.
3. Start a small emergency reserve
Even a modest reserve can provide a starting point. Increase it as your financial capacity improves.
4. Work on income growth
Developing a marketable skill, finding additional work or expanding an existing income source may ultimately have a greater effect than trying to eliminate every small pleasure from your budget.
Financial progress is not a competition.
Your first goal may simply be to stop consistently ending the month in a deficit.
What If You Support Family Members?
Family responsibilities are an important reality for many Nigerians.
Financial planning should not pretend otherwise.
If you regularly support parents, siblings, children or other relatives, include those obligations in your budget rather than treating them as unexpected expenses.
For example, if you normally send money home every month, make it a planned category.
You can also establish boundaries.
Helping family does not necessarily mean financing every request.
Before providing financial assistance, consider:
• Is this genuinely urgent?
• Can I afford to help?
• Will helping create a financial crisis for me?
• Is this a recurring problem?
• Is there another way to help?
A sustainable approach allows you to support others without permanently damaging your own financial foundation.
How to Save Money When Prices Keep Changing
A budget is not a document you create once and forget.
When prices rise or your circumstances change, your budget needs to change too.
Review your spending periodically.
If food, transportation or utilities become more expensive, identify where the additional cost will come from.
You may need to:
• Reduce discretionary spending
• Change purchasing habits
• Renegotiate certain services
• Find cheaper alternatives
• Increase income
• Adjust savings temporarily
• Reprioritize financial goals
However, avoid automatically sacrificing all savings whenever expenses increase.
If you stop saving every time life becomes more expensive, the habit can disappear completely.
A better approach is to adjust the amount while preserving the habit where possible.
Want to take your financial journey deeper?
Discover The Biblical Wealth Code and learn biblical principles for developing a healthier mindset toward money, wealth, stewardship, and financial responsibility.
Get The Biblical Wealth Code
Common Money-Saving Mistakes to Avoid
Let’s explore common money-saving mistakes to avoid, helping you reduce wasteful spending, make smarter financial choices, and save more effectively.
Mistake 1: Saving Without a Budget
You may save occasionally but still spend excessively elsewhere.
Better way: combine saving with spending awareness.
Mistake 2: Copying Someone Else’s Budget
A budget that works for a single person may not work for a family.
Best approach: build around your own income and obligations.
Mistake 3: Treating Every Discount as a Saving
Buying something you do not need is still spending.
Better approach: ask whether the purchase was necessary before considering the discount.
Mistake 4: Keeping No Emergency Reserve
Without emergency savings, unexpected expenses can force you into debt.
Best approach: build an emergency fund gradually.
Mistake 5: Investing Before Understanding the Investment
A promise of high returns does not eliminate risk.
The better way: research the investment, understand the risks and verify regulated operators where applicable.
Mistake 6: Increasing Spending Every Time Income Increases
More income does not automatically create more wealth.
Best way: increase savings and financial capacity alongside lifestyle improvements.
Mistake 7: Trying to Save What You Cannot Afford
An unrealistic savings target can cause you to abandon the entire plan.
Better approach: start with an amount you can sustain and increase it over time.
How to Turn These Tips Into a Monthly System
Knowing what to do is different from actually doing it.
Use this simple monthly routine.
Before the month begins
• Estimate your income.
• List fixed expenses.
• Estimate variable expenses.
• Identify upcoming large expenses.
• Set your savings target.
• Review debt payments.
• Decide what discretionary spending you can afford.
When income arrives
• Set aside planned savings.
• Fund important financial goals.
• Cover essential obligations.
• Allocate money for variable expenses.
• Keep discretionary spending within its limit.
During the month
• Track major expenses.
• Watch for impulse purchases.
• Compare actual spending with your plan.
• Adjust before a small problem becomes a large one.
At the end of the month
Ask:
1. Did I spend more than I earned?
2. Did I save what I planned?
3. Which category exceeded its limit?
4. What caused the overspending?
5. What unexpected expenses occurred?
6. What can I change next month?
7. Did my financial position improve?
That final review is extremely valuable.
A budget should become a feedback system, not merely a spreadsheet.
A 30-Day Money-Saving Challenge
If you want to put these personal finance tips into practice, start with a simple 30-day challenge.
Week 1: Discover
• Record every expense.
• Review your bank transactions.
• Identify unnecessary recurring expenses.
• List all debts.
• Calculate your average monthly income.
Week 2: Organize
• Create a realistic budget.
• Separate needs from wants.
• Set a savings target.
• Create categories for important upcoming expenses.
Week 3: Reduce
• Cancel unused subscriptions.
• Reduce unnecessary convenience spending.
• Compare prices before major purchases.
• Establish a waiting period for non-essential purchases.
Week 4: Build
• Transfer money into your emergency fund.
• Review your debt strategy.
• Set a longer-term savings goal.
• Identify one realistic way to increase income.
• Review your entire month’s spending.
At the end of the 30 days, do not focus only on how much you saved.
Look at what you learned about your financial behavior.
That knowledge can help you build better habits month after month.
How Saving Money Leads to Wealth Building
Saving is not the final destination.
It is part of the foundation.
A simplified wealth-building process looks like this:
Earn → Manage → Save → Protect → Invest → Grow → Repeat
First, you need income.
Then you need to manage that income effectively. Saving creates a reserve. An emergency fund protects against financial shocks. Once your foundation is stronger, appropriate investments may help your money pursue long-term growth.
This is why saving and wealth building should not be treated as completely separate subjects.
Frequently Asked Questions
1. What are the best personal finance tips to save money?
Start by understanding your income, tracking spending, creating a realistic budget, saving before discretionary spending, building an emergency fund, controlling recurring expenses, reducing unnecessary debt and gradually increasing income.
The best strategy is not necessarily the most complicated one. It is the one you can consistently apply.
2. How can I save money from a small salary?
Begin by identifying essential expenses and eliminating avoidable spending. Set a small but sustainable savings target and increase it when your income improves.
If your income is insufficient for basic needs, focus on income growth alongside expense management.
3. How much money should I save each month?
There is no single percentage that works for everyone.
The appropriate amount depends on your income, essential expenses, debt, dependants, emergency needs and financial goals.
A smaller amount saved consistently can be more practical than an aggressive target that you cannot maintain.
4. Should I save or invest first?
The answer depends on your financial circumstances.
Generally, money needed for immediate emergencies should be kept accessible rather than exposed to unnecessary investment risk. Once you have an appropriate financial reserve, you can consider investments based on your goals, time horizon and risk tolerance.
The Consumer Financial Protection Bureau (CFPB) advises investors to understand risk and conduct proper research before investing.
5. How can I manage money when my income is irregular?
Budget using conservative income estimates, prioritize essential expenses, build reserves during stronger months and avoid dramatically increasing your lifestyle whenever income temporarily rises.
A separate reserve can help smooth the differences between high-income and low-income months.
6. Is keeping money in a bank account the same as investing?
No. A savings or deposit account and an investment serve different purposes and have different risks, returns and accessibility characteristics.
For eligible deposits, Nigeria’s deposit-insurance framework provides protection subject to applicable coverage limits and conditions. Nigeria Deposit Insurance Corporation (NDIC) materials state that coverage levels depend on the type of insured institution and applicable rules.
Always verify current terms with the relevant institution and NDIC before relying on a particular coverage figure.
7. Should I avoid spending money on things I enjoy?
No. Good personal finance is not about eliminating every enjoyable expense.
The goal is to make discretionary spending intentional and affordable.
A sustainable financial plan should leave some room for enjoyment while protecting important goals.
Your Personal Finance Checklist
Before you finish this month, make sure you can answer yes to as many of these as possible:
o I know how much income I have available.
o I have tracked my spending.
o I have a realistic budget.
o I know my major unnecessary expenses.
o I have a savings target.
o I am building an emergency fund.
o I understand my debts and repayment obligations.
o I am controlling impulse purchases.
o I have planned for upcoming large expenses.
o I am working toward increasing my income.
o I understand the difference between saving and investing.
o I research investments before committing money.
o I avoid unrealistic or guaranteed-return investment promises.
o I review my financial progress regularly.
Your financial results are shaped by how you think about and use money. Explore a powerful wealth mindset shift that can help change financial habits, think long term, and build lasting wealth.
Conclusion
The most effective personal finance tips to save money are not necessarily complicated.
- Know what you earn.
- Know where your money goes.
- Plan before spending.
- Save intentionally.
- Protect yourself from emergencies.
- Control unnecessary expenses.
- Manage debt carefully.
- Increase your income where possible.
- And invest only after understanding what you are investing in.
Most importantly, do not measure financial progress solely by how much money you make.
Financial progress is also about how effectively you manage, protect and direct the money you already have.
You do not need a perfect financial life before you begin.
Start with one improvement. Track the result. Adjust your system. Then build on it.
Over time, these small decisions can create a stronger financial foundation and put more of your income toward the goals that matter to you.
Financial education is general information, not individualized financial, investment or tax advice. Financial discipline is equally important when applying money-management principles. Financial products, regulations, rates and tax rules can change, so verify current terms with the relevant Nigerian institution or a qualified professional before making significant financial decisions.
Looking for a faith-based approach to financial breakthrough?
7 Keys to Breaking Financial Limitations — 7 Midnight Prayers provides seven focused midnight prayers to help you seek God concerning your financial life.
Get the 7 Keys to Breaking Financial Limitation
Joy, also known as MindsetCoach, is the publisher and personal finance educator behind WealthMindset.com.ng, a Nigerian platform dedicated to practical money management and wealth-building education. She writes about budgeting, saving, financial literacy, debt management, investing, income growth, and building healthier financial habits. Through clear, practical, and evidence-informed content, Joy helps readers understand their money, make smarter financial decisions, and develop a wealth-building mindset suited to real-life financial challenges in Nigeria.
Hello Joy,
Just finished reading through this powerful piece, as someone trying to improve my financial knowledge, I found this post very useful. I like that it goes beyond simply saying “save more” and gives practical personal finance tips that can actually help with controlling expenses, increasing savings, and building wealth over time. The connection between everyday money habits and long-term financial freedom is especially important. A good read for anyone who wants to become more intentional with their money.
Hello Sammy Sir, thanks for stopping by with and encouraging words, keep vising, and keep sharing.